For an SBA 7(a) or 504 application

An SBA business plan built the way underwriters read one.

Twelve sections in the order an SBA loan package expects them, your county's real establishment counts, the lenders in your state that actually approved loans in your industry last year, and a debt service coverage ratio computed and printed on page one.
Build my SBA plan — preview free

$299 one time. No subscription. See your market analysis free, before you pay.

You only pay once you've read a real section of your own plan
  • U.S. Census Bureau
  • SBA 7(a) & 504 records
  • Bureau of Labor Statistics
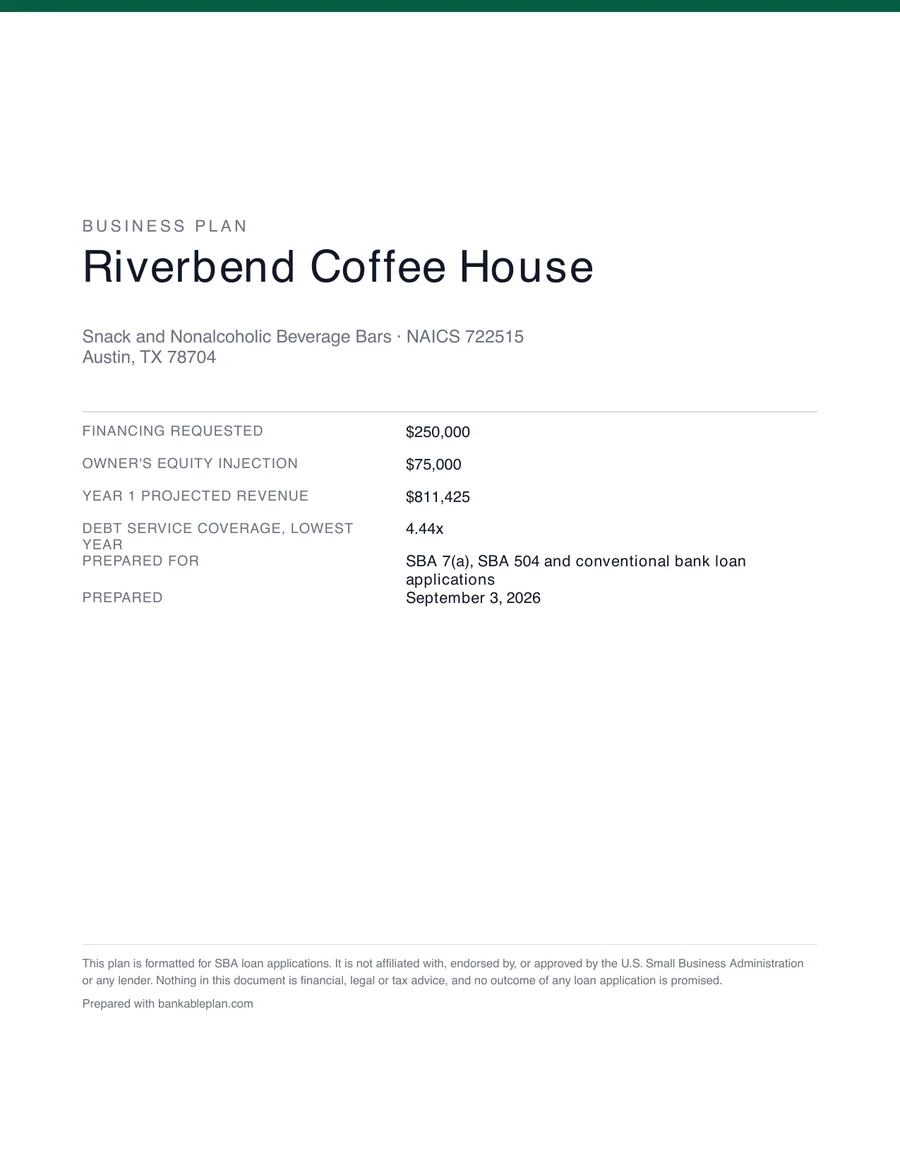
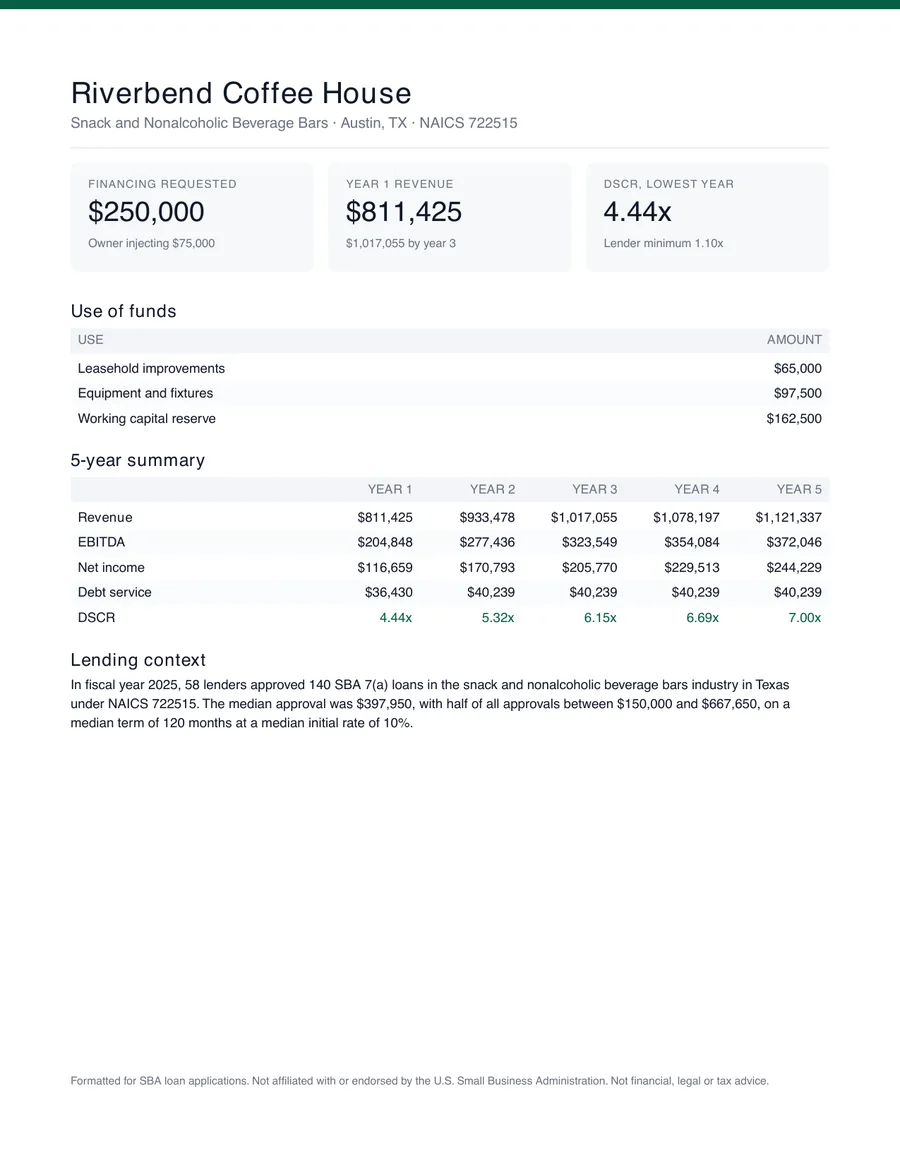
Plan cover page: the business name, its industry and NAICS code, the county, the amount requested, the owner equity, and the projected figures for the first years.One-page executive summary: the request, the use of funds, the coverage ratio, the key figures and the owner's background.Financial statements page: projected profit and loss across five years — revenue, cost of goods, gross profit, operating expenses, EBITDA, interest, taxes and net income.
Real pages from a plan this site produced — same engine, same layout, same numbers. The business shown is a worked example.
505,888
SBA 7(a) and 504 approvals indexed, through FY2025
3,144
U.S. counties with establishment data (CBP 2023)
1,192
industry codes with real SBA lending records
1.15×
the coverage ratio your plan is tested against before you pay

Why this one lands differently

Every generator writes text. Almost none of them bring data.

01

The competition actually in your county

Not “the restaurant industry is competitive”. The exact number of establishments on your NAICS code in your county, from County Business Patterns — a figure your lender can look up and check.

Travis County, Texas has 1,114 establishments in NAICS 722511 (Full-Service Restaurants). That is 8.17 per 10,000 residents against 6.64 statewide — a more crowded market than the state average. The average establishment in this industry in the county employs 28.4 people at an average annual wage of $32,575.
02

The lenders who actually fund your industry

The SBA publishes every approved 7(a) and 504 loan: the lender, the industry code, the state, the amount. We indexed all of it. Your plan names the banks that wrote loans like yours last year — and tells you where your request sits in the real distribution of what got approved.

In fiscal year 2025, 101 lenders approved 298 SBA 7(a) loans in the full-service restaurants industry in Texas under NAICS 722511. The median approval was $455,500, with half of all approvals between $150,000 and $999,175, on a median term of 120 months at a median initial rate of 10%.
The Huntington National BankNortheast BankNewtek Bank, National AssociationReadycap Lending, LLCPCB Bank

Nobody else does this. It costs us nothing — the data is public. It changes the conversation you walk into. Browse it free by state and industry.

03

The one ratio your banker checks first

Debt service coverage. Your cash flow divided by your loan payments. And the floor is not the same for everyone: SBA policy sets 1.10× for a 7(a) small loan, 1.15× for an expansion, and 1.25× for a business acquisition. We apply the one that fits your deal, print it on the first page, and — this is the part that matters — tell you before you buy if your plan doesn't clear it, and which lever to move.

Clears the floor
1.42×

Ship it.

Short by $18,400
0.94×

You hear it from us, not from your banker.

What lands in your inbox

Four files. Twelve sections. Five years that recalculate.

The pages below are from a plan this site actually produced.

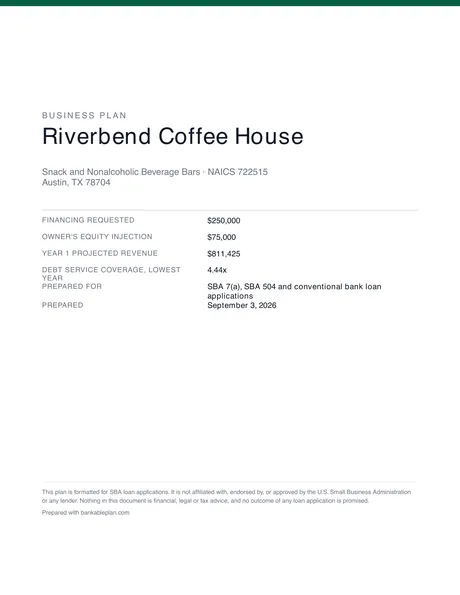
Plan cover page: the business name, its industry and NAICS code, the county, the amount requested, the owner equity, and the projected figures for the first years.

plan.pdf

The complete plan, laid out. This is what you hand over — and plan.docx is the same document, editable, because your accountant will want to touch it.

financials.xlsx

The model itself: monthly and annual, every cell a formula wired to the assumptions sheet. Your lender wants the model, not a picture of one.

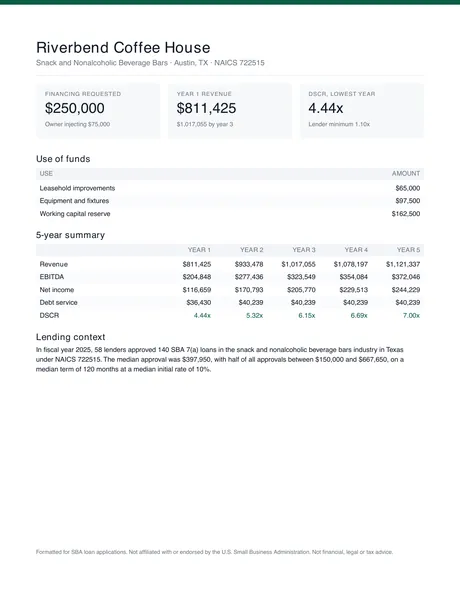
One-page executive summary: the request, the use of funds, the coverage ratio, the key figures and the owner's background.

one-pager.pdf

The one-page executive summary. Asked for at every first meeting, and often the only page that reaches the credit committee.

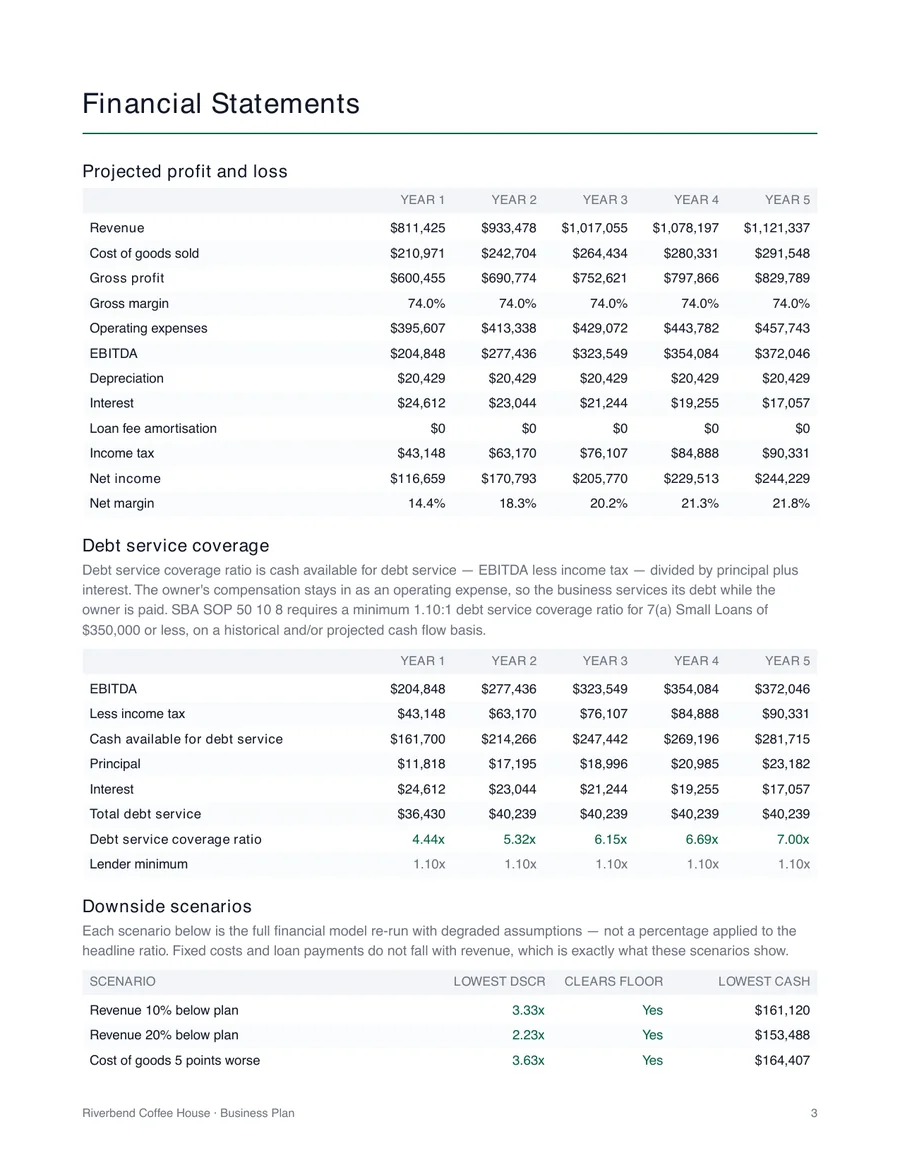
Financial statements page: projected profit and loss across five years — revenue, cost of goods, gross profit, operating expenses, EBITDA, interest, taxes and net income.

plan.pdf — financials

Five years of statements inside the plan itself — profit and loss, coverage, downside scenarios — so the package reads without opening a second file.

The twelve sections, in the order a loan package expects them
  1. 01Executive Summary
  2. 02Company Description
  3. 03Market Analysis — the real local data goes here
  4. 04Organization and Management
  5. 05Products and Services
  6. 06Marketing and Sales Strategy
  7. 07SWOT Analysis
  8. 08Risks and Mitigation — with the downside scenarios run
  9. 09Milestones and Timeline
  10. 10Funding Request — amount, use of funds, repayment
  11. 11Financial Projections — 5 years, monthly cash flow, balance sheet, ratios, DSCR
  12. 12Appendix — what to attach, and every data source named

Three steps. A quarter of an hour.

1

Tell us about the business

Five short screens. Industry, ZIP code, what you're asking for, how you make money, and who you are. About four minutes.

2

Read your market analysis, free

We pull your county's real establishment counts and the SBA lenders active in your industry, run the financial model, and show you the executive summary and market analysis. No card, no paywall.

3

Pay only if it's good

$299 unlocks the full twelve-section plan and all four files. If the model says your DSCR doesn't clear the floor that applies to your deal, or your equity injection is under the SBA's 10% minimum, we tell you that before checkout — not after.

What an SBA loan package actually asks for

A 7(a) or 504 application is not a pitch. The lender is not deciding whether your idea is exciting; they are deciding whether the cash flow services the debt, whether you can run the thing, and whether the collateral covers the downside. The plan is where they check the first two.

The order matters

Underwriters read in a fixed order, and a plan that arrives in a different one costs them time they will not spend. Executive summary, company description, market analysis, organisation and management, products and services, marketing and sales, funding request, financial projections, appendix. That is the order we produce, every time.

The ratio that decides it

Debt service coverage — your cash available for debt service divided by your principal and interest. The floor is not the same for every deal: SBA policy sets 1.10× for a 7(a) small loan of $350,000 or less, 1.15× for an expansion, and 1.25× for a first-time business acquisition or owner buyout. If your plan does not clear the one that applies to you, the file is declined or restructured, and you find out weeks later.

We compute it before you pay, using the threshold that applies to your transaction, print it on the first page, and tell you the size of the gap and which lever closes it: more revenue, lower operating cost, a larger equity injection so you borrow less, or a longer term. We check your equity injection against the SBA's 10% minimum at the same time.

Owner's compensation stays in

A projection that pays the owner nothing looks better and gets recomputed by the lender, who adds a market salary back and watches the coverage fall through the floor. Our model pays you the amount you say you need to live on, and the DSCR you see already carries it.

What we cannot do

We cannot promise a loan will be approved — nobody can, and anyone who does is selling something else. The SBA is a federal agency; it does not approve, endorse or certify business plan providers. What we do is make sure the document does not fail on the things a plan can control.
Straight about it

This does not replace a professional. It replaces the fortnight.

A consultant charges $500 to $3,000 and takes two weeks, most of it spent formatting numbers you supplied. You get that base in about ten minutes, for $299 — and you keep the file, editable, so a professional can review it instead of building it from nothing.

What you get

  • The twelve written sections, built around your own numbers
  • A five-year financial model that balances to the cent, with live formulas
  • Your county's real establishment counts and the SBA lenders active in your industry
  • The coverage ratio that applies to your deal, tested against downside scenarios
  • A personalised list of every document the lender will ask you for

What we do not do

  • We do not interview you

    A consultant spends two calls asking follow-up questions and challenging your assumptions. We ask five screens. If your numbers are optimistic, we bound them against industry ranges — we cannot tell you that your town will not support them.

  • We do not audit what you tell us

    The model computes from your figures. If the volume or the price is wrong, the projections built on them are wrong, and they will look confident anyway.

  • We do not obtain your documents

    Tax returns, the lease, the seller's financials, quotes, licences — only you can get those. We tell you exactly which ones and why.

  • We are not your accountant, attorney or immigration lawyer

    Nothing here is financial, legal, tax or immigration advice. For an acquisition or a visa filing, you want a professional reviewing the file before it goes in.

And if the loan is declined

No plan can promise financing, and we do not. Lenders weigh credit history, collateral, industry conditions, your experience and their own appetite that quarter — most of it outside any document. A declined application is not a refund event, and you should be wary of anyone who tells you otherwise. What we do guarantee is the work itself: if the files do not arrive, if a figure in the plan contradicts the model, or if the balance sheet does not balance, we refund in full. Read the refund policy.

Pricing

One payment. No subscription.

A consultant charges $500 to $3,000 for an SBA-ready plan and takes two weeks. An immigration consultant charges $2,000 to $5,000 for the E-2 version.

Everything included

Complete loan-ready plan

$299one time
  • All twelve sections, written around your real numbers
  • Census establishment counts for your county
  • The SBA lenders active in your industry and state, named
  • Five-year model: P&L, monthly cash flow, balance sheet, ratios, break-even
  • DSCR against the threshold that actually applies to your deal
  • Downside scenarios run through the model, not guessed
  • Your equity injection checked against the SBA 10% minimum
  • PDF, Word, one-pager, and a live Excel model with formulas
Start — see your preview free

You see your market analysis before you pay a cent. Refund policy.

+ $99 revision pack

Three regenerations within 30 days. Your banker asks for a change — you make it.

+ $199 E-2 / EB-5 version

The extra sections a visa filing needs: job creation, source of funds, five-year staffing.

Questions people actually ask

Is this an SBA-approved plan?

No — and be careful with anyone who says otherwise. The SBA is a federal agency; it does not approve or endorse business plan providers. What we do is format the plan the way SBA loan applications expect, in the section order underwriters read, with the ratios they check. Whether a loan is approved is your lender's decision, and nothing here promises an outcome.

Where does the market data actually come from?

Census County Business Patterns for establishment counts and payroll by industry and county. Census Population Estimates and Small Area Income and Poverty Estimates for population and median household income. SBA FOIA data — every approved 7(a) and 504 loan — for lender activity, approval amounts, terms and rates. Bureau of Labor Statistics QCEW for local wages. Every figure in your plan names its source, so your lender can check it.

Does an AI make up the financial projections?

No. That is the whole design. A deterministic engine written in TypeScript does every calculation — profit and loss, monthly cash flow, balance sheet, amortisation, taxes, break-even, ratios, DSCR, and the downside scenarios. The language model only proposes operating assumptions such as seasonality, and every assumption it proposes is clamped to published industry ranges before the engine sees it. Then the written sections are checked against the computed figures: any number that does not appear in the model is rejected and the section is rewritten.

What if my plan doesn't clear the coverage ratio?

You will see it before you pay, along with the size of the gap and which lever closes it — more revenue, lower operating cost, a bigger equity injection so you borrow less, or a longer term. The same applies to the SBA's 10% minimum equity injection, which we also check. We would rather lose the sale than sell you a plan that gets declined.

Is the Excel model really live, or just numbers pasted into a grid?

Live. Every cell below the assumptions sheet is a formula. Change the average ticket or the interest rate and the profit and loss, the cash flow, the balance sheet and the DSCR all recalculate. There is a balance check row that must read zero in all 36 months — including after you edit it.

How long does it take?

About four minutes to fill in the form. Generating the twelve sections takes eight to ten minutes — you can close the tab and come back, nothing is lost. The files are on your plan page as soon as it finishes.

Can I use it for an E-2 or EB-5 visa filing?

The base plan covers the business case. The E-2 / EB-5 add-on includes the extra sections those filings require — job creation projections, source of funds narrative, and a five-year staffing plan. It is not legal advice and does not replace an immigration attorney.

Which SBA programme is this for?

Both 7(a) and 504. The plan is the same document for either; what changes is the funding request section and the lending context, and both adapt to what you tell us. For 504 the plan also names the Certified Development Companies active in your state and the first-mortgage banks that partner with them.

Do I still need my lender's forms?

Yes. The plan is one piece of the package. You will still complete SBA Form 1919 and your lender's own application, and provide a personal financial statement, tax returns, and the lease or purchase agreement. The appendix lists everything to attach.

U.S. Census Bureau · SBA 7(a) & 504 records · Bureau of Labor Statistics

Your loan officer opens the spreadsheet before the prose.

Make sure it balances, covers its debt, and cites numbers they can check.

Start my plan — free preview

$299 one time, only after you've seen your own market analysis.